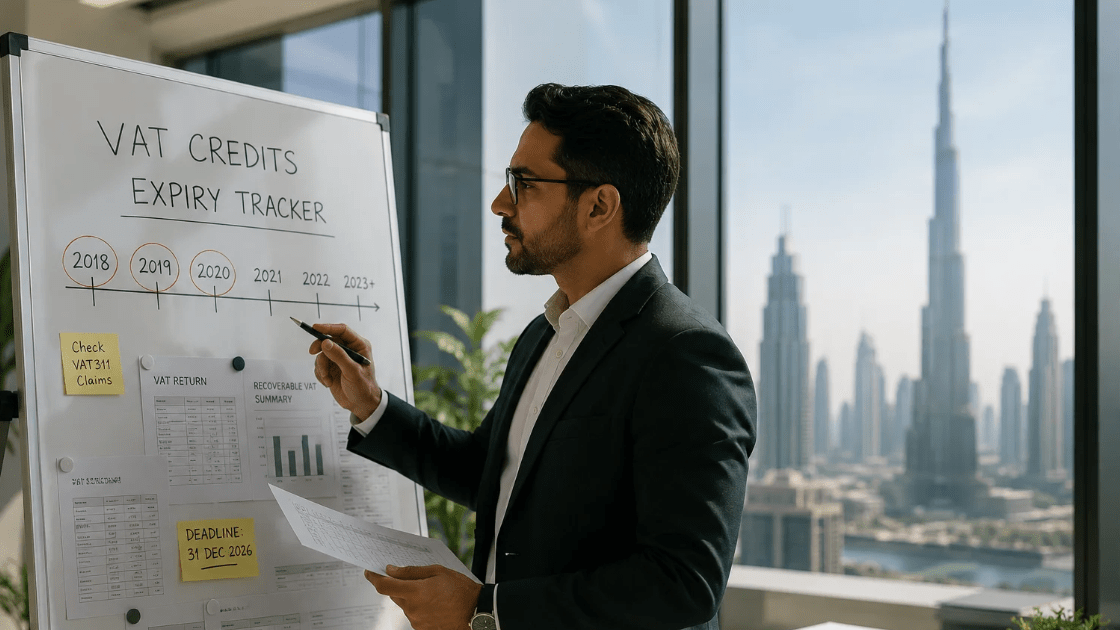
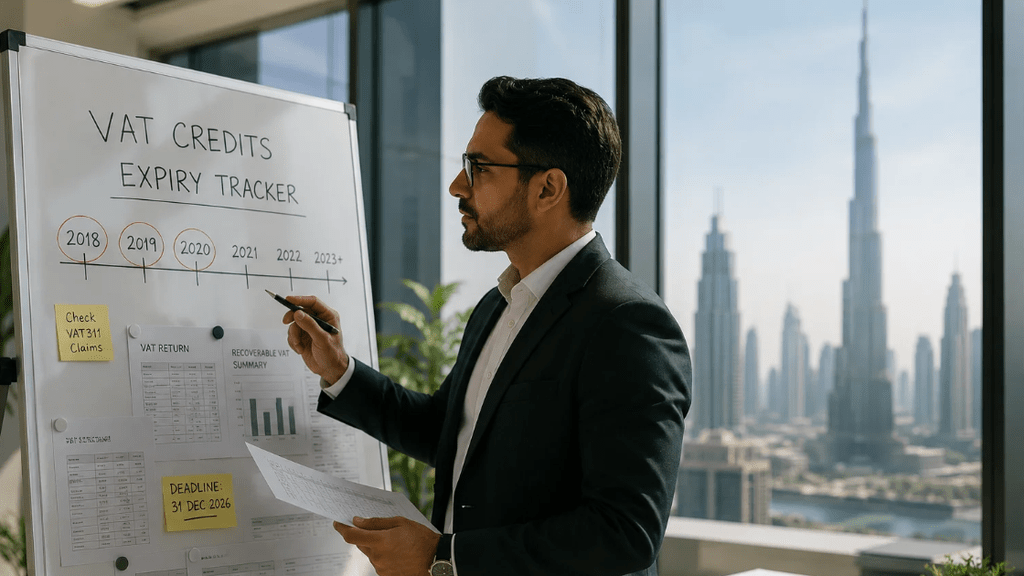
VAT credits accumulated by UAE businesses in 2021 are beginning to expire in 2026, under a five-year carry-forward limit that was introduced by the amended UAE Tax Procedures Law and that has caught a significant number of businesses by surprise. The rule, which caps the period during which excess VAT input tax credits can be carried forward at five years from the end of the tax period in which the excess arose, means that credits from 2021 tax periods that have not been claimed or offset will begin to lapse from their respective expiry dates through the course of this year. For businesses that have been carrying significant VAT credit balances, either because they have not been recovering them systematically or because they have been deferring refund applications in the belief that the credits would remain available indefinitely, the message from the amended Tax Procedures Law is stark: use your credits or lose them.
The five-year VAT credit expiry sits within a broader tightening of UAE tax compliance frameworks that has made 2026 the most consequential year for UAE business tax management since the introduction of VAT in 2018. Federal Decree-Law No. 17 of 2025, which rewrites the Tax Procedures Law effective January 2026, Federal Decree-Law No. 16 of 2025, which amends the VAT Law effective January 2026, and Cabinet Decision No. 129 of 2025, which unifies penalties across corporate tax, VAT and excise tax, together create a compliance environment that is significantly more structured and more unforgiving of inattention than the framework UAE businesses operated under in the early years of the tax system. The combination of these changes with the VAT credit expiry makes 2026 the year that UAE businesses which have not invested in professional tax management are most exposed to unexpected and material financial consequences.
“VAT credits from 2021 will start expiring in 2026. Businesses need to act before the window closes. The five-year limit on VAT input tax credit carry-forward was introduced as part of the Tax Procedures Law amendments, aligning the UAE’s VAT credit framework with international standards while creating an urgent compliance action for businesses with unrecovered credit balances.”
— Kayrouz and Associates, UAE Tax Changes 2026 (kayrouzandassociates.com, May 2026)
Which Businesses Are Most Exposed
The businesses most exposed to the 2021 VAT credit expiry are those that have accumulated significant input tax credits without systematically recovering them through refund applications or offsets against output tax liabilities. This pattern is more common than it might appear: businesses in capital-intensive industries that had significant build-out or equipment costs in 2021, real estate developers who incurred large VAT costs during construction phases, exporters whose output tax liability is low relative to their input tax costs, and businesses that experienced cash flow disruption in 2021 and deferred refund applications as a lower priority during that disruption are all categories that may have material credit balances approaching their expiry date.
The process for recovering expiring VAT credits requires a review of the business’s VAT records from 2021 to identify the specific credits at risk, a calculation of the expiry dates based on the tax periods in which those credits arose, and an application to the FTA for refund or offset within the relevant window. This is not a process that most businesses can manage without qualified tax advisory support: the documentation requirements, the FTA’s refund procedures and the calculation of the correct expiry dates all require expertise that goes beyond what a business owner or general finance team typically has available. Engaging a qualified UAE VAT specialist before the relevant credits expire is the correct immediate action for any business that has reason to believe it may be in this situation.
What the Broader Tax Tightening Means for UAE Business
The VAT credit expiry story sits within a broader pattern that every UAE business needs to understand: the UAE’s tax system is in a decisive enforcement phase that is different from the introductory and accommodation phase of its first several years. The FTA is matching corporate tax returns against VAT returns digitally. It is tracking supplier compliance chains to deny VAT reclaims where evasion has occurred. It is applying unified penalty frameworks across all tax types. And it is moving toward e-invoicing, which will require all large businesses to issue structured digital invoices through FTA-accredited service providers from January 2027. The businesses that have invested in professional tax management, that have clean VAT records, that file on time and that have the documentation to support their positions under audit are in a fundamentally different risk position from those that have not. The VAT credit expiry is the current most urgent expression of that difference, but it is not the last one.
“The UAE’s tax system has moved from a headline-grabbing introduction to full enforcement mode. In 2026, the Federal Tax Authority is auditing filings, issuing penalties, and tightening compliance expectations across mainland, free zone and offshore entities alike. The five-year VAT credit limit and the October VAT supply chain rule are the most immediate expressions of an enforcement trajectory that is only going in one direction.”
— BizHype Zone, UAE Corporate Tax 2026 Guide (bizhypezone.ae, June 2026)